
No prepayment penalty
No prepayment penalty means a borrower can pay off all or part of a loan before the due date without paying an extra fee to the lender. A no prepayment penalty clause states this right and how early payments are applied.
Analyze your contracts. Extract important clauses.
Try our AI contract analysis and extract important clauses and information from existing contracts.
Save your favourite clauses
Insert directly with a single click
Upload preferred precedents
Sample No prepayment penalty clauses
Source
Rivulet Media, Inc.The Company shall have the right to prepay the balance due hereunder in full or in part, at any time, with no prepayment penalty.
Source
Jacksam Corp (JKSM)Pre-Payment Terms: No prepayment penalty.
The Company has right to accelerate payments or prepay in full at any time with no prepayment penalty. This DL Note shall not be secured by any collateral or any assets of the Company.
There is no prepayment penalty under either Note.
Source
SPIRE INC (SR, SR-PA)While Spire has sufficient liquidity to cover its purchased gas costs it is taking steps to ensure that its financial flexibility is maintained. As a result, Spire Missouri has entered into a loan agreement (the “Loan Agreement”) with U.S. Bank, as administrative agent, and the lenders party thereto. The Loan Agreement provides a $250 million, 364-day unsecured term loan, maturing on March 22, 2022, with an interest rate based on LIBOR plus 65 basis points, which carries no prepayment penalty, and has the same covenants as our Revolving Credit Facility dated October 31, 2018 as amended. The foregoing summary of the Loan Agreement is not complete and is qualified in its entirety by reference to the full text of the Loan Agreement, which is attached hereto as Exhibit 10.1 and incorporated herein by reference.
As a result, no prepayment penalty was incurred in connection with this prepayment.
Source
CRH Medical CorpAdditionally, the remaining PPP Loan balance will carry a two year maturity date. There is no prepayment penalty on the PPP Loan.
The Note may be prepaid at any time before April 29, 2022 with no prepayment penalty.
Source
CUTERA INC (CUTR)There is no prepayment penalty. Under the terms of the PPP, all or a portion of the principal may be forgiven if the Loan proceeds are used for qualifying expenses as described in the CARES Act, such as payroll costs, benefits, rent, and utilities. No assurance is provided that the Company will obtain forgiveness of the Loan in whole or in part. With respect to any portion of the SBA Loan that is not forgiven, the SBA Loan will be subject to customary provisions for a loan of this type, including customary events of default relating to, among other things, payment defaults and breaches of the provisions of the Promissory Note.
Source
Chee Corp.The outstanding principal balance, plus accrued interest, is due and payable in a single balloon payment upon the Maturity Date. There is no prepayment penalty.
What does no prepayment penalty mean?
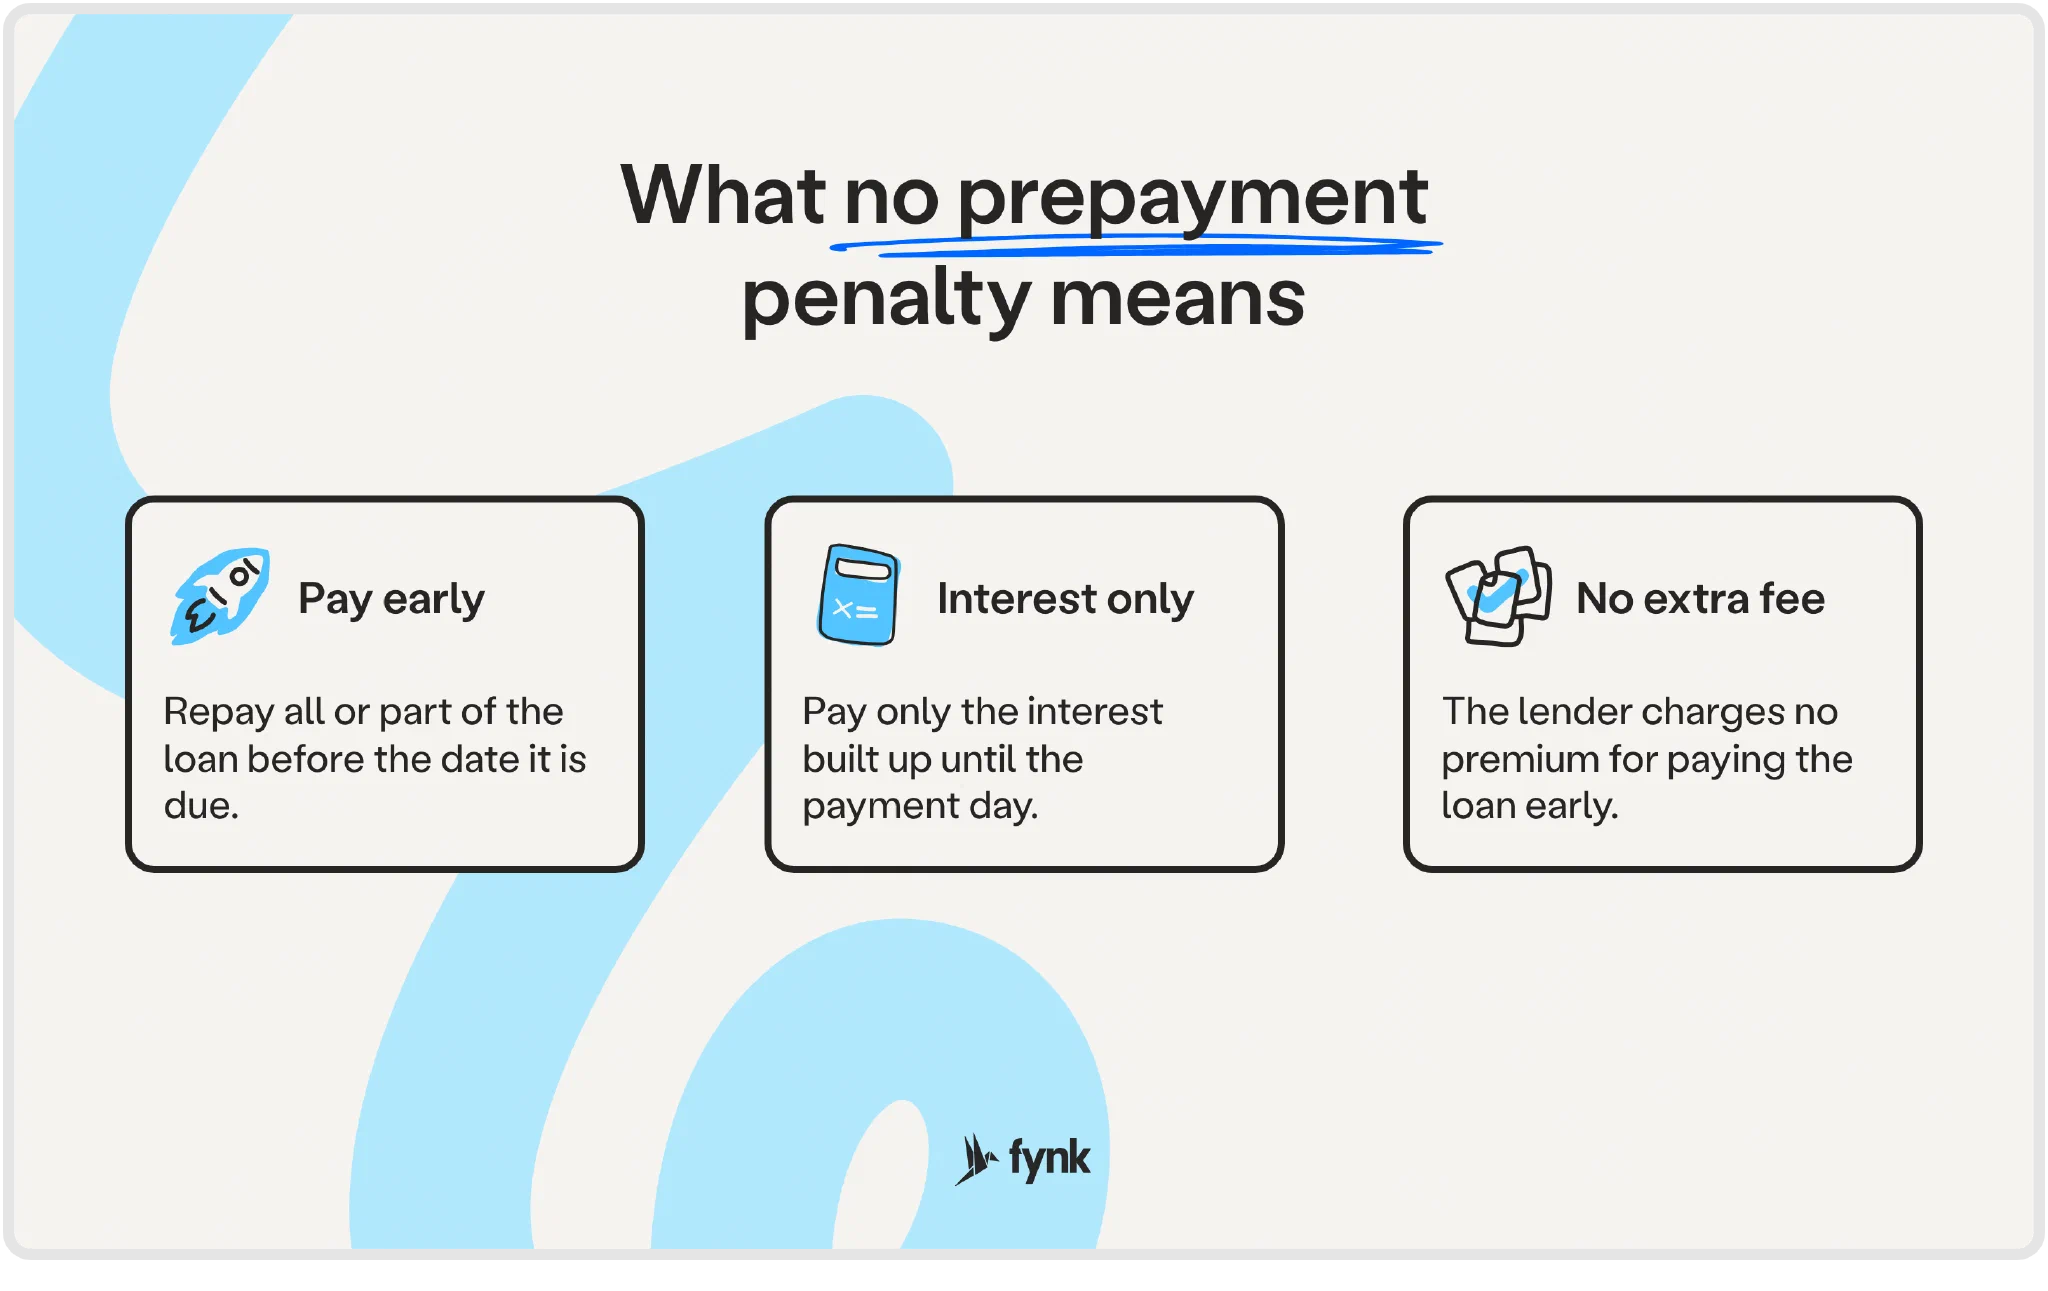
No prepayment penalty means the borrower can repay a loan early, in full or in part, without paying the lender an extra fee for doing so. The borrower only pays the principal and the interest that has built up until the payment date, and saves the interest that would have been due later.
It is a common feature of personal loans, auto loans, many mortgages and business loans, and lenders often advertise it as a selling point.
What is a prepayment penalty?
A prepayment penalty is a fee a lender charges when a borrower pays off a loan, or a large part of it, before the agreed schedule. It compensates the lender for the interest it will no longer earn. Common forms are:
- Percentage of the balance: for example 2% of the amount prepaid.
- Step-down: a fee that falls over time, for example 3% in year one, 2% in year two, 1% in year three.
- Months of interest: for example six months’ interest on the amount prepaid.
- Yield maintenance or defeasance: in commercial real estate loans, a payment that keeps the lender’s return as if the loan had run to maturity.
Are prepayment penalties allowed?
It depends on the loan and the country:
- US home loans: federal rules limit prepayment penalties on most residential mortgages. Where allowed, only on fixed-rate qualified mortgages that are not higher-priced, they are limited to the first three years and to 2% of the prepaid balance in the first two years and 1% in the third, and the lender must also offer a loan without a penalty.
- Germany: for fixed-rate consumer loans other than mortgages, early repayment compensation is capped at 1% of the amount repaid, or 0.5% if one year or less remains, and never more than the interest still due (§ 502 BGB). Mortgages have no fixed cap and can carry a larger “Vorfälligkeitsentschädigung” for the lost interest.
- Business loans: usually free to agree, so the loan agreement decides.
How to tell if a loan has a prepayment penalty
Look for a section titled “Prepayment”, “Voluntary prepayment” or “Early repayment” in the loan agreement or promissory note. In the US, the closing disclosure for a mortgage states whether there is one. Wording such as “may be prepaid in whole or in part at any time without premium or penalty” means there is none.
What a no prepayment penalty clause should include
- The right to prepay: in whole or in part, at any time or on payment dates.
- No fee: without premium, penalty or breakage cost.
- Notice: how many days in advance the borrower must tell the lender, if any.
- Application: how partial prepayments are applied: to principal, to the next installments, or to the last ones.
- Accrued interest: that interest to the prepayment date must be paid with it.
No prepayment penalty clause example
Sample clause: No prepayment penalty
Add this clause to a contract, send it and get it signed in fynk.
Use it in fynk for freeHow to compare loan terms across agreements
When a company has several loans, the cheapest one to repay first is the one without a penalty and with the highest rate. In fynk, prepayment terms, rates and maturity dates are fields in each loan agreement, so AI search finds the loans you can repay freely, and the contract calendar shows any notice deadline for a prepayment.
Which contracts contain a no prepayment penalty clause?
Promissory notes, personal, auto and business loans, mortgages, convertible loans and credit agreements. These free templates include one:
Free templates with this clause
- Unsecured promissory note template The borrower may prepay all or part of the note at any time without premium or penalty. Use template
- Convertible loan agreement template The company may prepay the loan and accrued interest at any time without penalty, unless the lender has already chosen to convert. Use template
- Master promissory note template The borrower may prepay all or any part of the principal of the note without penalty. Use template
Related clauses
- Prepayment A prepayment clause outlines the terms under which a borrower can pay off a loan or portion of it before its due date without facing penalties. This clause often specifies any conditions or fees associated with early payments, helping borrowers manage their financial obligations more flexibly.
- Acceleration clause An acceleration clause lets a lender demand the whole remaining balance of a loan at once, instead of in monthly payments, if the borrower defaults. It is standard in mortgages, promissory notes and business loans, and it usually comes with a notice and a chance to cure before the lender can use it.
- Default interest rate A default interest rate clause stipulates the interest rate that will be applied to overdue payments in a contract. This rate serves as a financial penalty, incentivizing timely payments and compensating the party owed for any delay.
- Late payment penalty A Late Payment Penalty clause stipulates that if a payment is not made by its due date, the party responsible for the payment will incur an additional fee or penalty. This clause incentivizes timely payments and compensates the payee for any inconvenience or financial impact caused by the delay.
Frequently asked questions
For the borrower, yes. It lets you repay early, refinance or sell without an extra fee, and saves interest. Loans without a penalty sometimes carry a slightly higher rate, so compare the total cost.
Many personal loans in the US do not, but some lenders charge one. Check the loan agreement or ask the lender before signing.
A prepayment penalty applies when you repay a loan early. An early termination fee applies when you end a service or lease contract early. Both compensate the other side for income it loses.
Often, yes, especially for business loans. Lenders may drop it in exchange for a slightly higher rate or fees, or agree to a penalty that falls each year.
More clauses from the library
See allNo refunds
A no refund policy says that once a customer has paid, they cannot get their money back, for example because they changed their mind. It is legal in many cases if the customer sees it before buying, but it cannot override consumer rights such as refunds for faulty goods or legal cooling-off periods.
15 example clauses
No reverse engineering
The "No Reverse Engineering" clause prohibits any attempts to deconstruct, disassemble, or otherwise analyze a product, software, or system to obtain underlying trade secrets or proprietary information. This clause is designed to protect intellectual property by preventing unauthorized access to the technology's source code or structural makeup.
21 example clauses
No smoking
A "No Smoking" clause prohibits individuals from smoking within certain designated areas or premises, aiming to maintain a smoke-free environment for health and safety reasons. This clause may apply to all forms of smoking, including cigarettes, cigars, and electronic vaping devices, and often outlines potential penalties for violations.
12 example clauses
Analyze your contracts. Extract important clauses.
Try our AI contract analysis and extract important clauses and information from existing contracts.
Save your favourite clauses
Insert directly with a single click
Upload preferred precedents