
IRS Form 8594
IRS Form 8594, the Asset Acquisition Statement under Section 1060, reports how the price of a business bought as assets is split across seven asset classes. Buyer and seller each attach it to their tax return for the year of the sale, and asset purchase agreements usually contain a clause on how both sides agree that split.
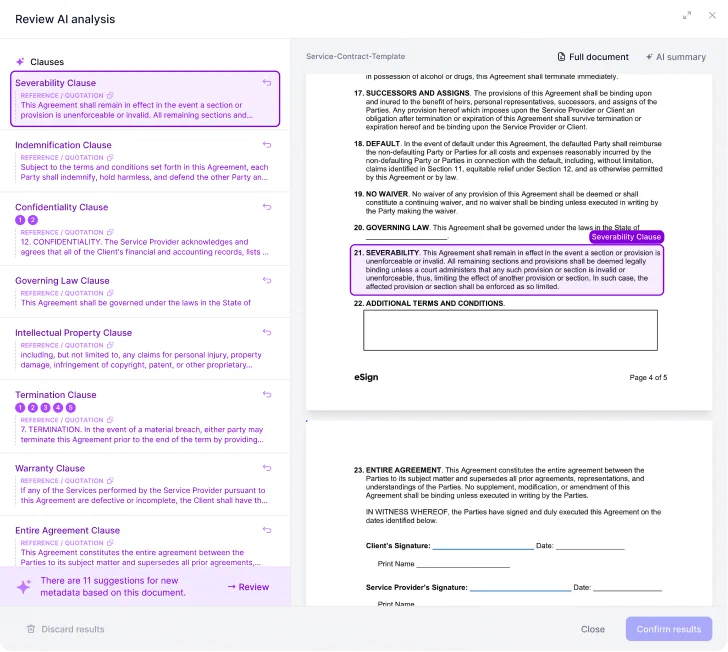
Analyze your contracts. Extract important clauses.
Try our AI contract analysis and extract important clauses and information from existing contracts.
Save your favourite clauses
Insert directly with a single click
Upload preferred precedents
Sample IRS Form 8594 clauses
Source
BALLANTYNE STRONG, INC.The IRS Form 8594, including all information that has been agreed to or finally determined by the Accounting Firm pursuant to this Section 5.1(a), shall be referred to as the “Final Allocation.” Each of Buyer and Seller shall prepare and file all Tax Returns consistent with, and shall not take any Tax position inconsistent with, the Final Allocation, except as otherwise required by a “determination” within the meaning of Section 1313 of the Code (or applicable state or local Legal Requirement), or the execution of an IRS Form 870-AD.
Source
KeyStar Corp. (KEYR)Allocation of Purchase Price. Within ninety (90) days after the Closing, Purchaser will deliver a proposed draft of IRS Form 8594 to Seller allocating the Purchase Price and all other relevant items, as determined for U.S. federal income tax purposes, among the Purchased Assets (the “Purchase Price Allocation Schedule”). The Purchase Price Allocation Schedule will be prepared in accordance with Code Section 1060 and the Treasury Regulations promulgated thereunder. Purchaser and the Seller shall report, act and file all tax returns (including, but not limited to, IRS Form 8594) in all respects and for all purposes consistent with the Purchase Price Allocation Schedule. No party shall take any position for tax purposes (whether in audits, tax returns, or otherwise) that is inconsistent with such Purchase Price Allocation Schedule unless required to do so by final determination within the meaning of Section 1313(a) of the Code.
A Designation Agreement designating the “reporting person” for purposes of completing IRS Form 1099 and, if applicable, IRS Form 8594.
BUYER and SELLER acknowledge that each party may be required to report this transaction to the Internal Revenue Service (IRS) and allocate the Purchase Price among the applicable asset classifications found on IRS Form 8594.
BUYER and SELLER agree to complete, sign, and submit the appropriate IRS form 8594 for this transaction.
Seller shall have delivered to Buyer a Bill of Sale for all Purchased Assets and an IRS allocation of purchase price (IRS Form 8594).
BMC and AMI covenant and agree that (a) BMC and AMI shall file all tax returns (including, but not limited to, IRS Form 8594) consistent with the allocation above and (b) neither BMC nor AMI will take any tax position before any governmental body or in any proceeding with respect to tax that is in any way inconsistent with such allocation; provided, however, that nothing contained herein shall prevent BMC or AMI from settling any proposed tax deficiency or adjustment by any governmental body based upon or arising out of the allocation, and neither BMC nor AMI shall be required to litigate before any court any proposed tax deficiency or adjustment by any governmental body challenging such allocation
Such allocation shall be according to generally accepted accounting principles and set forth on IRS Form 8594.
The parties agree that this allocation of the Purchase Price shall be conclusive and binding, and each party hereby covenants and agrees to use such allocation for all purposes, including tax returns. Such Allocation Schedule may be attached in draft form at Closing and replaced with a final schedule within one hundred twenty (120) days after Closing. A copy of the completed IRS Form 8594 shall be executed by Asset Seller and Asset Buyer and be included in their respective tax returns.”
Purchase Price Allocation. Buyer shall prepare a draft IRS Form 8594, allocating the Option Premium, Purchase Consideration and all other relevant items, as determined for U.S. federal income Tax purposes, to the assets of the Company in accordance with the allocation methodology attached hereto as Schedule 1.10, which methodology has been mutually agreed to by the parties hereto, and which the parties agree is consistent with Code Section 1060 and the Treasury Regulations promulgated thereunder (and any similar provisions of state, local, or non-U.S. Law). Buyer shall deliver such draft IRS Form 8594 to Representative no later than [***] days after the final determination of the Purchase Consideration in accordance with this Section 1.10. Buyer shall timely file IRS Form 8594 in accordance with such draft IRS Form 8594 and the Company, and the Unitholders and Representative, shall file all other Tax Returns in a manner consistent with such draft IRS Form 8594. Neither Buyer nor any of the Unitholders shall take any position for Tax purposes (whether in audits, Tax Returns, or otherwise) that is inconsistent with such final IRS Form 8594 unless otherwise required by applicable Law, provided that the parties may use a different methodology for financial reporting purposes.
Allocation. Each Party shall independently timely file IRS Form 8594 reflecting its determination with respect to the allocation (the “Allocation”) of the Payment (and all other amounts treated as consideration for U.S. federal income tax purposes) among the assets treated as sold by the Manager to the Company for U.S. federal income tax purposes, and neither Party’s determination shall bind the other Party with respect to its determination of the Allocation. The Allocation shall be reasonable and shall be made in accordance with Section 1060 of the Internal Revenue Code of 1986, as amended. Neither Party shall be unreasonably impeded in its ability and discretion to negotiate, compromise and/or settle any tax audit, claim or similar proceedings in connection with the Allocation.
What is IRS Form 8594?
IRS Form 8594, the “Asset Acquisition Statement Under Section 1060”, reports how the purchase price of a business bought as a group of assets is allocated across seven asset classes. The buyer uses the allocation to set the tax basis of each asset, and the seller uses it to work out the gain on each one, so both sides want it to favor them.
The form has three parts:
- Part I: general information, the other party, the date of sale and the total sales price.
- Part II: the original allocation across Classes I to VII, plus two questions: whether buyer and seller agreed the allocation in the sales contract or another signed document, and whether the deal also included a non-compete, license, lease, employment or similar agreement with the seller.
- Part III: a supplemental statement when the price changes after the sale.
Who has to file Form 8594?
Generally, both the buyer and the seller file Form 8594 when a group of assets that makes up a trade or business changes hands and the buyer’s basis is determined only by the amount paid. Each side files its own form, and the two should match.
You do not file it when the whole group of assets is exchanged in a like-kind exchange under Section 1031, or for the transfer of a partnership interest. A purchase of all partnership interests that is treated as an asset purchase under Revenue Ruling 99-6 still needs the form.
When is Form 8594 due?
Attach Form 8594 to your income tax return for the year in which the sale took place, so it is due with that return, including extensions. You only file it again in a later year if the consideration goes up or down, for example through an earn-out or a price adjustment. In that case you file a new form with Part III for each year the change happens.
The seven asset classes on Form 8594
| Class | What it includes |
|---|---|
| I | Cash and general deposit accounts, but not certificates of deposit |
| II | Actively traded personal property, certificates of deposit and foreign currency, such as government securities and listed stock |
| III | Assets marked to market at least once a year and debt instruments, including accounts receivable |
| IV | Inventory and property held mainly for sale to customers |
| V | All assets not in another class, such as equipment, furniture, vehicles, buildings and land |
| VI | Section 197 intangibles except goodwill, such as customer lists, licenses, trademarks and a workforce in place |
| VII | Goodwill and going concern value |
How the residual method allocates the price
The price is allocated in class order, never above an asset’s fair market value, and whatever is left over goes to goodwill. That is the residual method required by Section 1060.
For example, a buyer pays $1,000,000 for a business:
| Class | Asset | Fair market value | Allocated |
|---|---|---|---|
| I | Cash | $20,000 | $20,000 |
| III | Accounts receivable | $80,000 | $80,000 |
| IV | Inventory | $150,000 | $150,000 |
| V | Equipment | $300,000 | $300,000 |
| VI | Customer list | $200,000 | $200,000 |
| VII | Goodwill and going concern | Residual | $250,000 |
The allocation has real tax effects. Inventory and equipment are recovered quickly, while Class VI intangibles and Class VII goodwill are amortized over 15 years. A seller usually prefers more in goodwill, which is mostly taxed as capital gain, and less in inventory or recaptured depreciation, which is taxed as ordinary income.
The purchase price allocation clause in an asset purchase agreement
Because both sides file their own Form 8594, an asset purchase agreement usually settles the allocation in a clause, as the examples above show. If buyer and seller agree the allocation in writing, the agreement binds both of them for tax purposes unless the IRS finds it inappropriate (Treasury Regulation 1.1060-1(c)(4)).
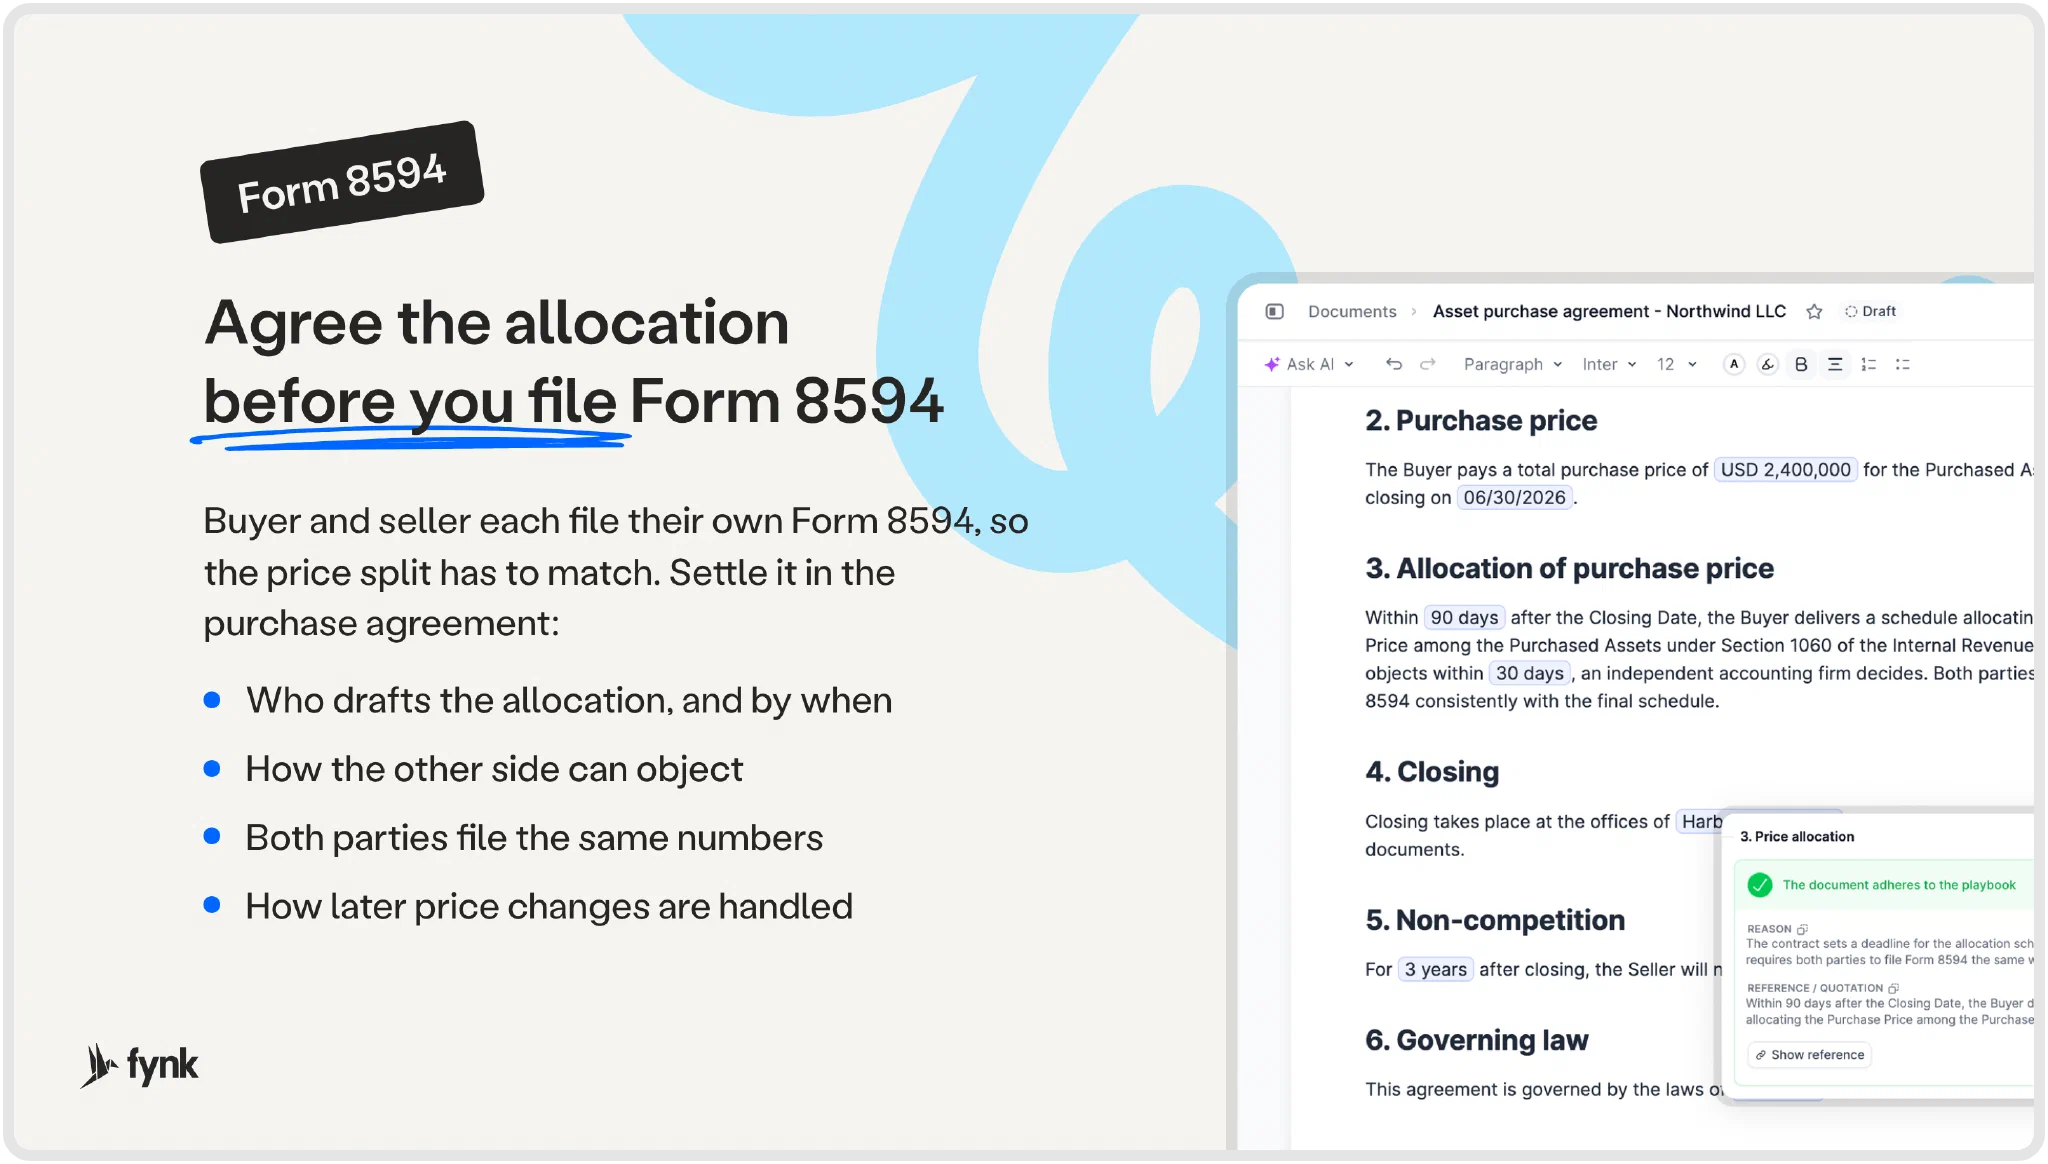
A good allocation clause answers four questions:
- Who prepares the first draft, usually the buyer, and by when, for example 90 or 120 days after closing.
- How the other side can object and who decides a dispute, often an independent accounting firm.
- That both parties file consistently with the final allocation and take no contrary tax position.
- How later price changes are reflected, including earn-outs and working capital adjustments.
Sample clause: Allocation of purchase price
Add this clause to a contract, send it and get it signed in fynk.
Use it in fynk for freeThe 90-day and 30-day windows are easy to miss once the deal has closed. In fynk you can set deadline reminders on the signed business asset purchase agreement, so the allocation schedule and the Form 8594 are ready before the tax return is due.
Which contracts need an allocation clause?
Any sale of a business or a group of assets for one price. None of these free templates has an allocation clause yet, so add the sample above:
Free templates to add this clause to
 Business asset purchase agreement template
Sets one total price for furniture, equipment, inventory, receivables and goodwill. Add the clause to split it across the asset classes.
Use the free template Asset purchase agreement (APA) template
Covers the sale of a software business's tangible and intangible assets. Most of the price lands in Classes VI and VII.
Use the free template Real estate sales contract template
Already allocates the purchase price to each property, the same idea Form 8594 applies to every asset class.
Use the free template
Related clauses
- Earnout An earnout clause is a contractual provision typically used in business acquisitions, where part of the purchase price is contingent on the future performance of the acquired business. This clause aims to bridge valuation gaps by aligning the seller's compensation with the business's success post-acquisition, often based on specific financial targets or milestones.
- Taxes and duties The "Taxes and Duties" clause specifies that each party is responsible for its own taxes and duties associated with the execution and performance of the contract. It may also outline the obligations for withholding taxes and state any requirements for the provision of tax-related documents.
- No tax advice The "No Tax Advice" clause disclaims any responsibility for providing tax-related guidance or advice within the scope of the agreement. It advises parties to consult their own tax professionals to address their specific tax concerns or obligations.
- Closing costs Closing costs are the various fees and expenses incurred during the finalization of a real estate transaction, often including charges such as loan origination fees, appraisal fees, title insurance, and escrow deposits. These costs can be negotiated between the buyer and seller, with each party potentially responsible for certain expenses as outlined in the purchase agreement.
Frequently asked questions
Yes. If you fail to file a correct Form 8594 by the due date of your return and cannot show reasonable cause, you may be subject to penalties under sections 6721 through 6724 of the Internal Revenue Code.
No. You file it once, with the tax return for the year of the sale. You only file again in a later year if the purchase price increases or decreases, using Part III as a supplemental statement.
Form 8594 reports an actual purchase of business assets under Section 1060. Form 8883 reports a stock purchase that is treated as an asset purchase under a Section 338 election, and it is filed by the old and new target corporation.
They file separately, but the amounts should match. An allocation agreed in writing in the purchase agreement binds both sides, and mismatched forms are a common reason for IRS questions.
More clauses from the library
See allJob title and duties
The "Job Title and Duties" clause outlines the specific position an employee is hired for, detailing the title and primary responsibilities associated with the role. This clause helps ensure clarity in expectations and scope of work, serving as a reference point for performance evaluations and potential role changes.
7 example clauses
Joint and several liability
Joint and several liability means that two or more parties share an obligation, and each of them can be made to pay the whole amount. The creditor can collect from any one of them, who can then claim the others' shares back.
20 example clauses
Joint and several obligations
Joint and several obligations refer to a legal arrangement where multiple parties are collectively and individually responsible for fulfilling a contractual obligation. This means that a creditor can demand the full performance or payment from any of the involved parties, rather than just their proportional share.
8 example clauses
Analyze your contracts. Extract important clauses.
Try our AI contract analysis and extract important clauses and information from existing contracts.
Save your favourite clauses
Insert directly with a single click
Upload preferred precedents