
Certificate of trust: meaning, contents and uses
Updated · Published
A certificate of trust, also called a certification of trust, is a short document signed by the trustee that confirms a trust exists and states who the trustee is and what they may do. Banks, title companies and brokers accept it instead of the full trust agreement, so the beneficiaries and the trust’s terms stay private.
- Certificate of trust
- A short document, signed by the trustee, that confirms a trust exists and summarises the facts a third party needs to deal with it: the name and date of the trust, who the trustee is and what the trustee is allowed to do. It is used instead of handing over the full trust agreement, so the beneficiaries and the distribution terms stay private. Many state statutes call it a certification of trust.
This entry describes the general position in the United States, where certificates of trust are most common. State rules differ, so check the statute of the state whose law governs the trust, and ask an estate planning attorney before relying on a form.
Certificate of trust vs certification of trust
The two terms mean the same thing in practice. “Certification of trust” is the term used in the Uniform Trust Code and in many state statutes. Banks, title companies and attorneys also use certificate of trust, abstract of trust, memorandum of trust, trust certificate or affidavit of trust, depending on the state and the institution.
Not to be confused with the certificate of trust that forms a Delaware statutory trust. That one is a public filing with the Delaware Secretary of State (under 12 Del. C. § 3810) that creates a business entity, mostly used in finance and real estate investment. It has nothing to do with the privacy document described here.
What a certificate of trust contains
Section 1013 of the Uniform Trust Code, which many states have adopted in some form, lists the information a certification of trust may contain:
- The trust’s existence and the date the trust instrument was signed
- The identity of the settlor (also called grantor or trustor), the person who created the trust
- The identity and address of the currently acting trustee or trustees
- The powers of the trustee, for example to buy, sell, mortgage or lease property, or to open accounts
- Whether the trust is revocable, and who holds the power to revoke it
- The signing authority of co-trustees: whether one trustee can sign alone or all must sign together
- The trust’s taxpayer identification number (for a revocable living trust, often the settlor’s Social Security number)
- How title to trust property should be taken, for example “Jane Doe, Trustee of the Doe Family Trust dated March 1, 2020”
The certification must also state that the trust has not been revoked, modified or amended in any way that would make its statements incorrect.
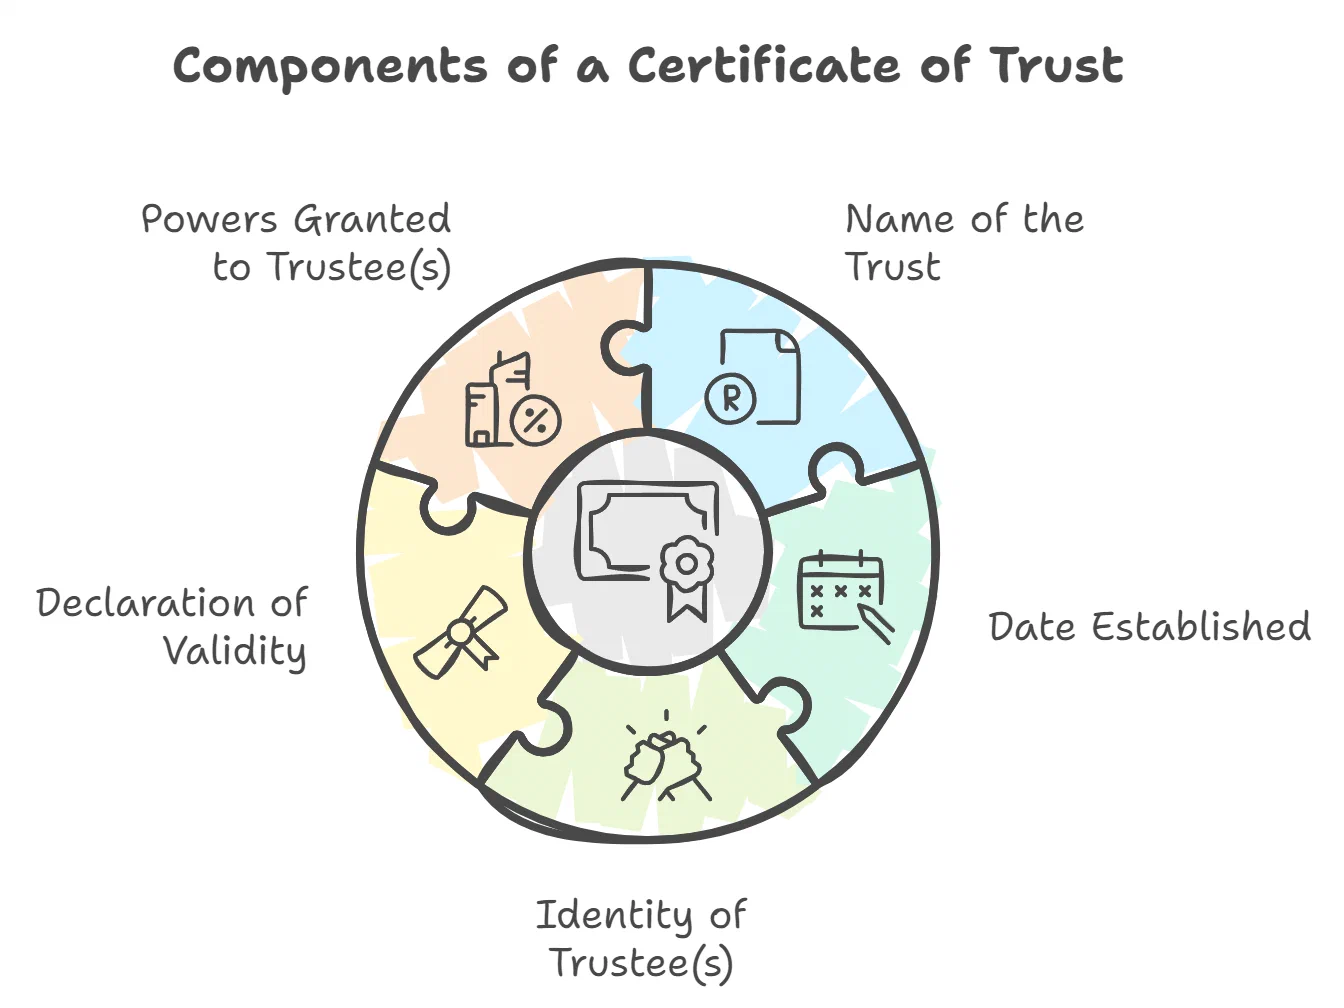


The key components of a Certificate of Trust.
What it leaves out: the dispositive terms, meaning who the beneficiaries are, what they receive and when. The trust’s assets are not listed either. That is the main reason the document exists.
Why banks and title companies ask for one
A trust cannot sign anything. The trustee acts for it. Anyone who deals with the trustee wants proof that the trust is real and that this person may act for it, before they move money or property. Typical situations:
- Opening or retitling a bank or brokerage account in the name of the trust
- Buying, selling or refinancing real estate held in the trust, where the title company and lender need to see the trustee’s authority
- Transferring assets into the trust after it has been set up
- Dealing with insurers, transfer agents or retirement plan administrators
- A successor trustee taking over after the original trustee dies or becomes incapacitated
The certificate is also good for the recipient. Under the Uniform Trust Code model, a person who relies on a certification in good faith, without knowing it is wrong, is not liable for doing so and may enforce the transaction as if the statements were true. A recipient may ask for excerpts of the trust that name the trustee and give the power for the transaction at hand. A recipient who demands the full trust agreement on top of that can be liable for damages if a court finds the demand was not made in good faith.
In practice, many institutions still have their own certification forms and may insist on them.
Certificate of trust vs full trust agreement
| Certificate of trust | Trust agreement | |
|---|---|---|
| Purpose | Proves the trust exists and who may act for it | Creates the trust and sets all its terms |
| Length | Usually one to three pages | Often dozens of pages |
| Names beneficiaries | No | Yes |
| Shows assets and distributions | No | Yes |
| Signed by | The trustee or trustees | The settlor (and usually the trustee) |
| Shown to | Banks, title companies, brokers, other third parties | The trustee, beneficiaries, attorneys, courts |
| Needs updating | When trustees change or the trust is amended in a relevant way | When the settlor changes the trust |
Who signs a certificate of trust
The trustee signs it, not the beneficiaries. In a revocable living trust, the settlor is often also the first trustee, so in practice the person who created the trust signs. After the settlor’s death or incapacity, the successor trustee signs a new certificate.
The rules on how many trustees must sign differ by state:
- Uniform Trust Code model: any trustee may sign or otherwise authenticate the certification.
- California (Probate Code § 18100.5): the certification must be an acknowledged declaration signed by all currently acting trustees, which means it is notarized.
Even where the statute does not demand it, banks and title companies usually expect the signature to be notarized, and a certificate that will be recorded with a county recorder needs to meet that office’s recording requirements.
Signing for someone else always raises the question of authority. The same logic applies to companies: see who can sign for a company and how to sign as power of attorney.
State differences
Most states have a statute on certifications of trust, many based on Section 1013 of the Uniform Trust Code, but the details vary:
- What must be included. Some states list the facts as optional (“may include”), others make some of them mandatory, such as the taxpayer identification number.
- Extra items. California, for example, allows the certificate to include the legal description of real property held in the trust.
- Who signs and whether it must be notarized. See above.
- Recording. In some states a certification can be recorded in the land records together with a real estate transfer. Once recorded, it becomes a public record.
Check the statute and any form the bank or title company requires before preparing the document.
How to get a certificate of trust
- Ask the attorney who drafted the trust. Many estate planning attorneys prepare a certificate of trust together with the trust agreement.
- Or prepare it yourself from your state’s statute or the institution’s own form, using the information in the trust agreement.
- Sign it before a notary if your state or the recipient requires it.
- Keep signed originals and copies, and give the institution what it asks for.
- Update it when a trustee changes, the trust is amended in a way that affects the certificate, or a successor trustee takes over.
Whether a certificate of trust can be signed electronically or notarized remotely depends on the state and on whether the bank, title company or county recorder accepts it. Electronic signatures are valid for most transactions in the US (see are electronic signatures legally binding), but recipients of trust documents often still ask for a notarized paper original.
Related terms
- Trust agreement: the full legal document that creates the trust and sets out its terms.
- Trustee: the person or institution that manages the trust according to its terms.
- Successor trustee: the trustee who takes over when the original trustee can no longer act.
- Settlor (grantor, trustor): the person who creates the trust and transfers assets into it.
- Beneficiary: the person who benefits from the trust.
- Revocable living trust: a trust the settlor can change or cancel during their lifetime, the most common reason for a certificate of trust.
For real estate held in trust, the certificate usually travels alongside the real estate sales contract and the deed, signed by the trustee in their role as signatory.
Frequently asked questions
It proves to a third party, such as a bank, broker or title company, that a trust exists and that the trustee may act for it. It is used to open or retitle accounts, buy, sell or refinance property held in the trust, and when a successor trustee takes over.
Yes, in practice. Certification of trust is the term used in the Uniform Trust Code and in many state statutes. Certificate of trust, abstract of trust and memorandum of trust are other names for the same kind of document.
It depends on the state and the recipient. California requires an acknowledged declaration signed by all acting trustees. Other states have no notarization requirement in the statute, but most banks and title companies still expect a notarized signature.
No. It does not need to include the dispositive terms, meaning the beneficiaries and what they receive. That privacy is the main reason to use a certificate instead of the full trust agreement.
Under statutes based on the Uniform Trust Code, a recipient may ask for excerpts that name the trustee and grant the power for the transaction. A recipient who demands the full trust agreement on top of a certification can be liable for damages if a court finds the demand was not made in good faith. In practice, banks often have their own forms and policies.
Usually the estate planning attorney who drafted the trust, or the trustee using the state statute or the bank's own form. It is signed by the trustee or trustees, not by the beneficiaries.
Take control of your agreements. Move your business forward.
Run agreements the way they should run: fast, clear, and on your terms.
No setup headaches
Go live in days, not quarters
No lock-in
Full export anytime
No hidden fees
Signatures included, no envelope fee